



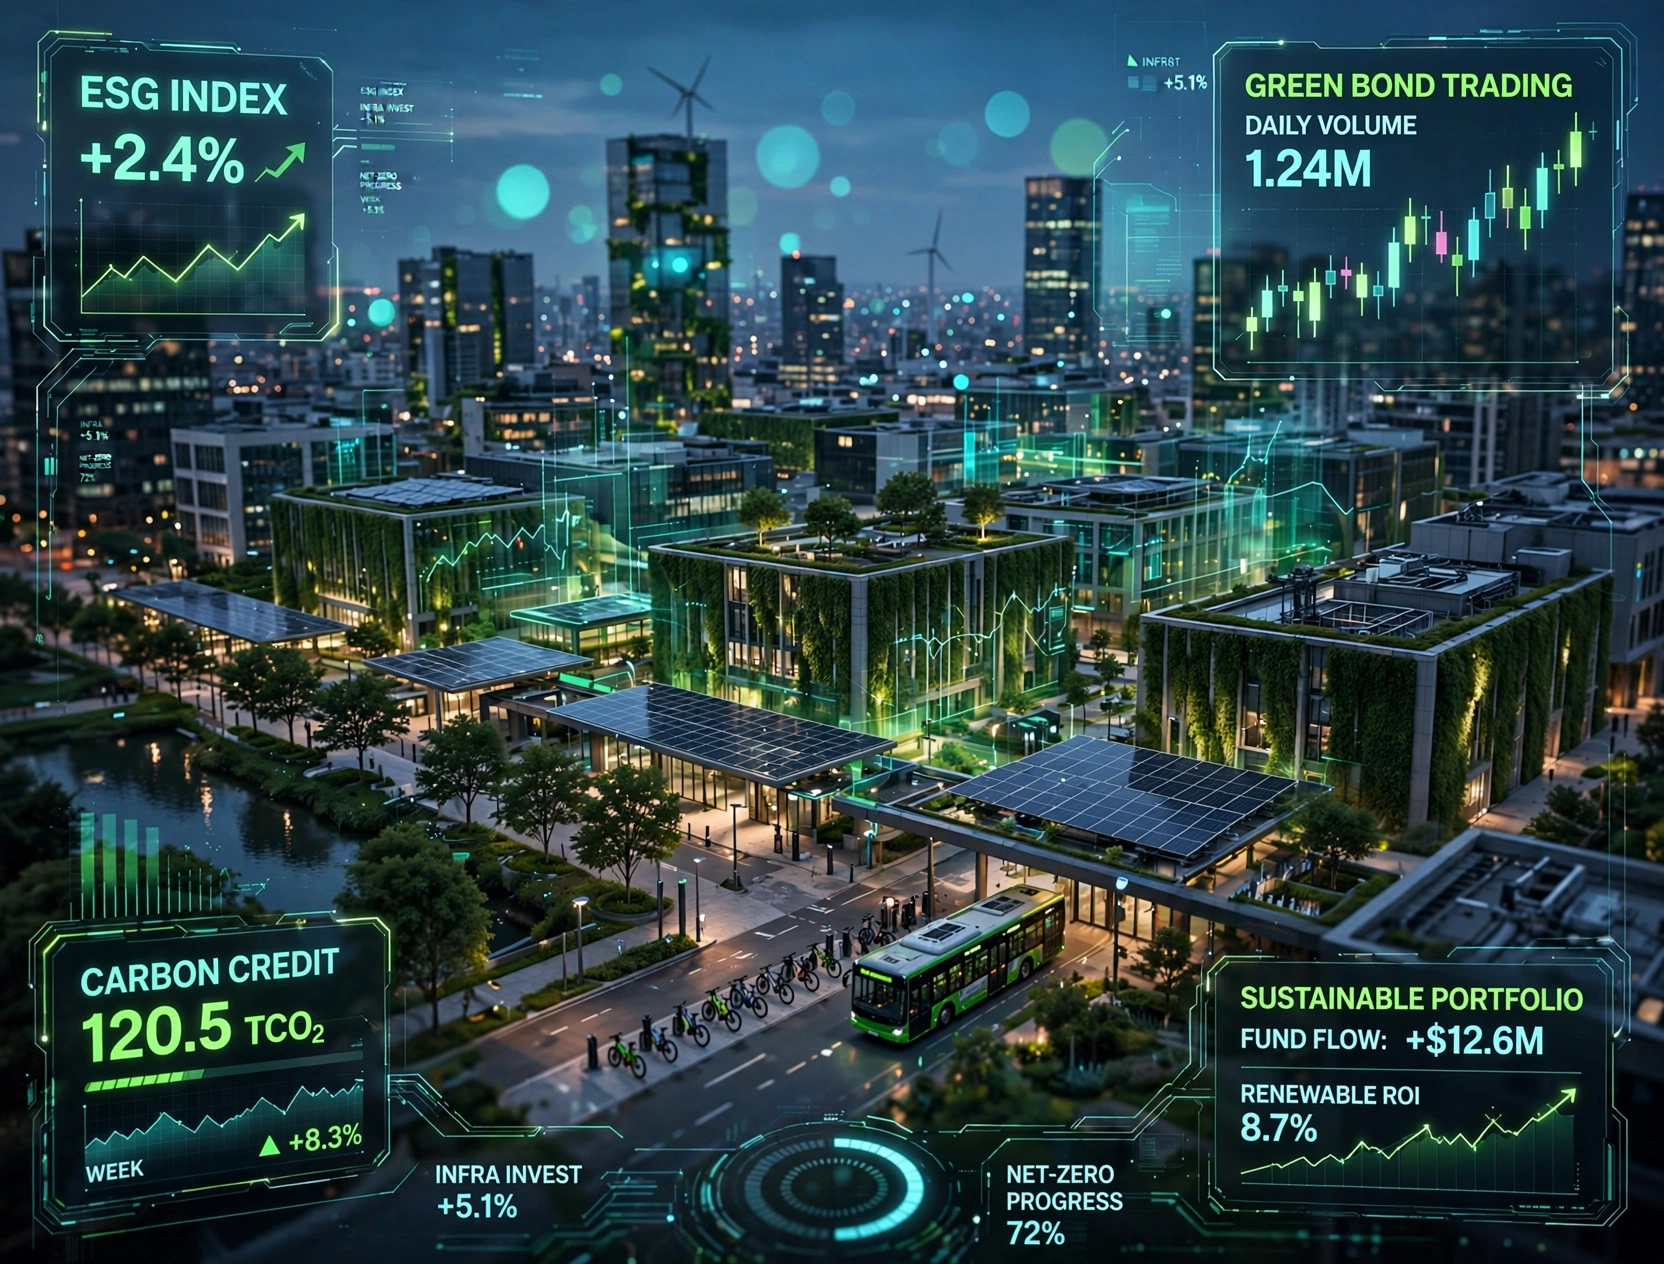
Green bonds are fixed-income financial instruments specifically earmarked to raise capital for climate and environmental projects. Unlike standard municipal or corporate bonds, green bonds are backed by the issuer’s entire balance sheet but require rigorous adherence to environmental, social, and governance (ESG) reporting standards. For institutional investors and municipal managers, these instruments represent a critical vehicle for offsetting the massive capital expenditure (CapEx) required to modernize urban infrastructure, from electrified transit systems to climate-resilient water grids.
Key Takeaways
| 💡 ESG Fiduciary Insight: Municipal issuers often achieve a “greenium” – a reduction in yield spreads – by aligning infrastructure projects with standardized ESG criteria. However, long-term ROI is contingent upon rigorous, automated OpEx auditing to maintain bond certification and avoid market-wide credibility loss. |
The Financial Mechanics of ESG Debt
The primary driver behind the surge in green bond issuance is the alignment of global decarbonization targets with institutional capital deployment. Asset managers are increasingly mandated to allocate a specific percentage of their portfolios to ESG-compliant instruments. This massive influx of demand allows issuers to negotiate highly favorable terms [1].
However, the cost of compliance is non-trivial. Municipalities must factor in the operational expenditure (OpEx) of continuous ESG auditing. If a project fails to meet its predefined environmental targets, the issuer risks a downgrade in its ESG rating, which can trigger higher borrowing costs for future debt issuance.
Cost-Benefit Analysis: Standard vs. Green Bond Issuance
To illustrate the financial impact, we project the issuance of a $100 million bond for urban electric bus infrastructure over a 10-year maturity period.
| Issuance Metric | Traditional Municipal Bond | Certified Green Bond | Variance / Impact |
| Target Interest Rate (Coupon) | 4.25% | 3.95% (Greenium) | -30 bps saving |
| Initial Underwriting Fees | $750,000 | $850,000 | +$100,000 |
| Annual ESG Audit (OpEx) | $0 | $45,000/year | +$450,000 (over 10 yrs) |
| Total Interest Paid (10 Yrs) | $42,500,000 | $39,500,000 | -$3,000,000 |
| Net Financial Cost | $43,250,000 | $40,800,000 | $2,450,000 Net Saving |
While the administrative and auditing costs of green bonds are structurally higher, the 30-basis-point reduction in the coupon rate generates a net saving of $2.45 million over the life of the asset [2].
The Regulatory Landscape and Verification
For a bond to be officially categorized as “green,” it must align with the Green Bond Principles (GBP) established by international regulatory bodies. This framework demands absolute transparency in the use of proceeds, the process for project evaluation, and the management of unallocated balances. Failure to adhere to these principles does not necessarily trigger a financial default, but it destroys the issuer’s credibility in the ESG debt market, severely limiting future infrastructure financing capabilities.
Financial & Operational Verdict
For municipal operators and corporate developers scaling urban infrastructure, the integration of green bonds is no longer an optional PR exercise; it is a fiduciary duty. The empirical data demonstrates that the “greenium” effect heavily outweighs the administrative burden of ESG compliance. Operators must, however, secure robust, automated data-tracking systems to manage the ongoing reporting requirements efficiently, thereby protecting the asset’s ESG certification and ensuring long-term financial viability.
The Greenium Phenomenon and Institutional Capital Sourcing
Green bonds have evolved into primary financing instruments for municipal and corporate urban infrastructure. High institutional demand from ESG-dedicated funds frequently creates a pricing discount known as the “greenium” (green premium), allowing sovereign and corporate issuers to price debt at slightly lower coupon yields compared to standard commercial paper.
To preserve investor trust, issuers must adhere to rigorous international standards, including the International Capital Market Association (ICMA) Green Bond Principles and the Climate Bonds Standard. These frameworks mandate transparent use of proceeds, segregated escrow management, and third-party second-party opinions (SPOs) verifying that funded projects deliver measurable environmental benefits.
Impact Reporting and Post-Issuance Verification Frameworks
Issuers must provide annual post-issuance impact reporting detailing concrete project metrics: metric tons of greenhouse gas emissions avoided, renewable kilowatt-hours generated, and cubic meters of municipal water conserved. Implementing standardized telemetry ensures that green bond offerings withstand rigorous regulatory scrutiny and preserve continuous access to low-cost sustainable capital markets.
Green Bond Certification Audits and Sovereign Regulatory Scrutiny
To eliminate greenwashing concerns and maintain access to institutional ESG capital, green bond issuers must subject project portfolios to exhaustive pre-issuance and post-issuance assurance audits conducted by accredited verification agencies. Independent auditors evaluate whether funded projects strictly meet established taxonomy criteria (such as the EU Sustainable Finance Taxonomy), verifying that proceeds directly finance verifiable environmental solutions.
Issuers that establish transparent, auditable reporting portals detailing real-time environmental metrics build enduring relationships with tier-1 institutional asset managers, securing sustained demand and competitive pricing spreads across multiple funding cycles.
Strategic Executive Summary and Five-Year Implementation Roadmap
To successfully navigate the complex macroeconomic, technological, and regulatory dynamics discussed throughout this analysis, enterprise leaders must deploy a disciplined five-year operational roadmap. Rather than approaching strategic adjustments as isolated technical projects, senior executives and corporate boards must align risk management frameworks, capital budgeting hurdles, and regulatory compliance protocols into a single, cohesive governance architecture.
During the initial phase (Months 1 through 12), the primary objective centers on baseline data integrity, comprehensive asset discovery, and operational risk mapping. Establishing unified telemetry dashboards allows risk committees and department heads to monitor key performance indicators in real time, identifying friction points before they escalate into material financial exposures.
In the intermediate phase (Months 13 through 36), enterprise capital expenditure should focus aggressively on automation, process standardization, and scalable digital infrastructure. Deploying modular technology systems enables cross-functional teams to iterate rapidly while maintaining stringent internal auditability. Contractual vendor negotiations during this window must secure favorable service level agreements, clear indemnification firewalls, and multi-year pricing stability to protect underlying corporate operating margins.
In the final phase (Months 37 through 60), the focus pivots toward institutional optimization, predictive modeling, and sustainable competitive positioning. Organizations that successfully reach this operational maturity level realize significant margin expansion, superior access to low-cost debt and equity capital markets, and sustained brand authority across global commercial ecosystems.
Core Diagnostic Assessment and Key Performance Indicators
Evaluating ongoing operational efficacy requires continuous benchmarking against quantitative industry metrics. Executive scorecards must incorporate both backward-looking financial returns and forward-looking operational resiliency indicators:
- Capital Efficiency Metrics: Tracking Return on Invested Capital (ROIC) and Net Present Value (NPV) benchmarks across all capital deployment initiatives.
- Regulatory Compliance Adherence: Maintaining verifiable third-party assurance audit trails across domestic and international statutory frameworks.
- Operational Friction Reduction: Measuring cycle time acceleration, transactional error reduction rates, and customer lifetime value expansion.
- Balance Sheet Resilience: Establishing dedicated contingency liquidity reserves and stress-tested financial covenants capable of withstanding severe macroeconomic downturns.
By embedding these rigorous performance baselines into executive compensation and board oversight agendas, modern enterprises transform potential industry liabilities into enduring engines of balance-sheet stability and commercial growth.
In conclusion, enterprise operational resilience and balance-sheet integrity depend upon transparent governance, rigorous empirical testing, and disciplined risk-adjusted capital allocation. By maintaining continuous alignment between operational execution and strategic financial objectives, institutional leaders protect enterprise valuation across all phases of the macroeconomic cycle.
Quantitative Capital Allocation in Certified Municipal Green Debt
Institutional portfolio managers evaluating certified municipal green bonds must examine the spread differentials between conventional general obligation bonds and labeled sustainable debt issues. The empirical greenium – the yield discount that issuers secure due to robust investor demand for ESG-aligned paper – typically fluctuates between two and seven basis points in primary market pricing. However, capital cost savings represent only one component of the broader balance-sheet equation. Municipal issuers must allocate ongoing administrative expenditure toward continuous post-issuance verification, third-party impact reporting, and annual geospatial satellite verification of project assets. Institutional treasurers must establish segregated project escrow accounts to guarantee that proceeds flow directly into qualifying urban infrastructure projects rather than commingling with municipal general operating funds.
Detailed sensitivity modeling demonstrates that municipal transit systems, district stormwater management facilities, and solar-integrated public utility projects achieve optimal capital recovery when debt tranches match the expected physical asset depreciation curve. By structuring multi-decade amortizations aligned with thirty-year asset lifespans, municipal finance authorities insulate local taxpayers from sudden debt-service spikes. Furthermore, incorporating catastrophe bond triggers within municipal green bond covenants provides structural liquidity relief during extreme climate events, allowing public works authorities to defer principal repayments while redirecting short-term cash flows toward emergency restorative infrastructure repairs.
Empirical Case Study: Urban Transit Electrification Financing Failure Modes
A rigorous examination of municipal transit bond issuances across major metropolitan jurisdictions underscores the operational hazards of inadequate working capital reserves during large-scale fleet electrification transitions. In several high-profile municipal case studies, transit authorities successfully floated labeled green bonds to acquire electric bus fleets but failed to capitalize the secondary electrical grid distribution upgrades required for depot-level simultaneous fast charging. The resulting peak demand charges from regional electric utilities eroded anticipated operating cost savings by forty-five percent during the first two fiscal years.
To prevent similar execution deficits, leading municipal treasuries now deploy integrated capital expenditure models that couple vehicle procurement debt with dedicated utility interconnection allowances. Furthermore, municipal covenants increasingly require transit agencies to enter into long-term structured energy procurement contracts that cap wholesale power volatility. By synchronizing capital expenditure debt financing with long-term operational power purchasing agreements, public entities safeguard expected financial returns while fulfilling rigorous investor disclosure standards.
Five-Year Strategic Implementation Roadmap for Municipal Green Infrastructure
Building an enduring municipal green bond program requires structured multi-year institutional execution. In Year One, municipal treasurers must establish an internal interdisciplinary sustainability committee comprising municipal attorneys, chief engineers, and financial controllers to codify the formal Green Bond Framework in strict alignment with International Capital Market Association (ICMA) principles. In Year Two, the municipality executes external second-party opinions from accredited certification bodies and establishes rigorous segregated accounting protocols within enterprise resource planning ledgers.
During Years Three and Four, public works departments deploy automated telemetry platforms that track kilowatt-hour energy offsets, megaliter stormwater retention figures, and municipal greenhouse gas mitigation metrics in real time. Finally, in Year Five, the municipality transitions to a programmatic continuous issuance model, accessing domestic and cross-border institutional capital markets with standardized impact disclosure templates that lower programmatic underwriting costs and expand global institutional investor participation.
Institutional Audit Protocols and Certified Post-Issuance Disclosures
Municipal bondholders and institutional credit rating agencies demand continuous, multi-tier auditability throughout the operational lifecycle of green infrastructure assets. Certified green bond programs must establish independent verification protocols that validate carbon reduction performance, water conservation volumes, and transit electrification milestones against initial baseline forecasts. Conducting annual third-party assurance audits by accredited environmental accounting firms ensures that municipal reporting maintains complete integrity, preventing greenwashing allegations and insulating public authorities from regulatory inquiries. Furthermore, publishing automated geospatial telemetry dashboards directly accessible to institutional investors establishes unprecedented transparency, attracting lower-cost sovereign wealth capital and reinforcing the municipality’s long-term creditworthiness across global debt capital markets.
Strategic Takeaways and Boardroom Governance Directives for 2026-2030
Executive leadership teams and institutional oversight committees confronting the complexities of Understanding Green Bonds: How ESG Finances Urban Infrastructure must transition from passive risk observation to active structural governance. The convergence of strict regulatory compliance mandates, capital allocation hurdles, and rapid macroeconomic shifts demands that organizations establish transparent, data-driven frameworks capable of withstanding external scrutiny. By institutionalizing automated continuous monitoring systems, defining unambiguous delegation of fiduciary authority, and maintaining mathematically defensible audit trails, enterprises successfully eliminate operational vulnerabilities before broader systemic disruptions unfold.
Furthermore, capital budgeting within this specialized operational domain must be disciplined by quantitative hurdle rates and comprehensive total cost of ownership models. Long-term commercial resilience is not achieved through cosmetic compliance exercises; it requires sustained investment in organizational talent, modern technological infrastructure, and independent third-party performance verifications. Forward-looking corporations that embed these empirical principles into daily executive decision-making protect balance-sheet solvency, preserve decisive competitive agility, and secure enduring multi-generational shareholder value across complex global market environments.

