



What Is Aircraft Leasing Economics?
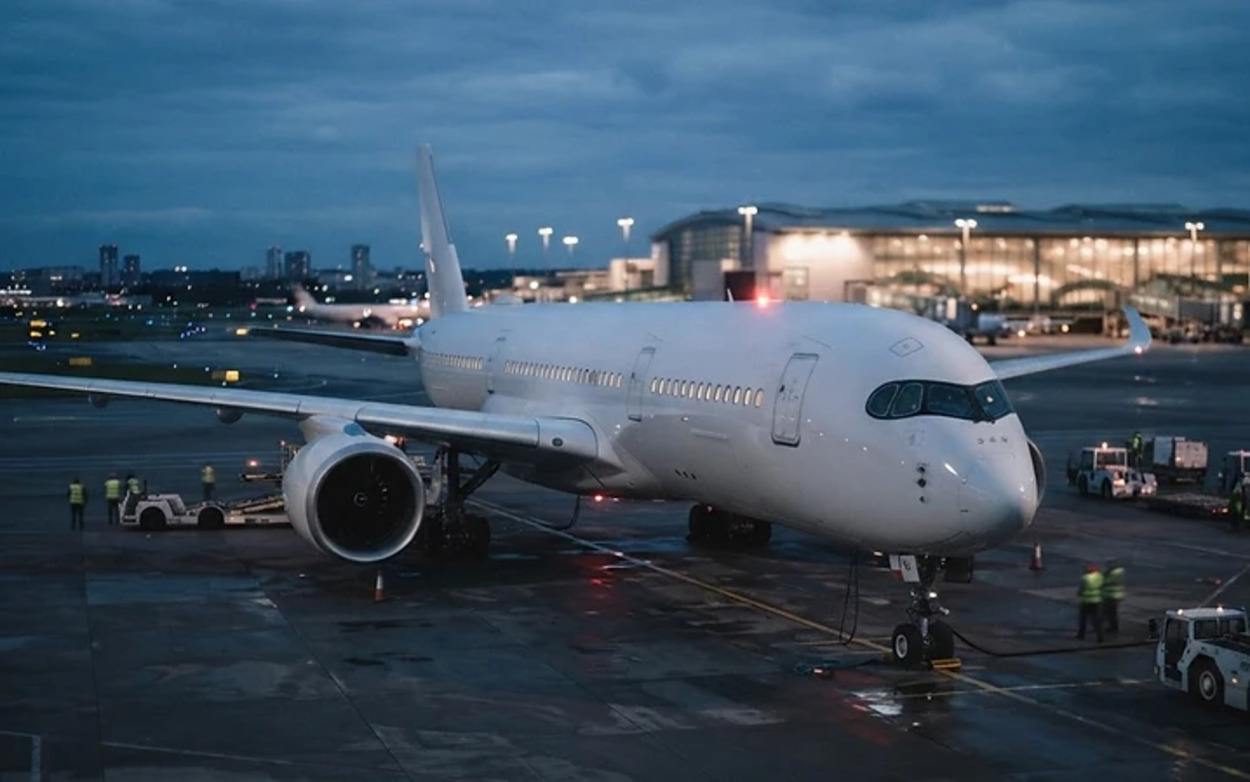
Aircraft leasing economics is the analytical framework used to evaluate the cost, risk, and capital-efficiency trade-offs between owning, debt-financing, and leasing commercial aircraft. In 2026, roughly 48% of the global commercial fleet is operated under lease rather than outright ownership, a structural shift driven by the capital intensity of next-generation airframes and the post-pandemic re-leveraging of airline balance sheets [1].
Key Takeaways
The Lease Rate Factor and Its Determinants
The lease rate factor (LRF) expresses monthly rent as a percentage of the aircraft’s base value. A $50 million A321neo leased at a 0.95% factor costs the operator $475,000 per month, or roughly $5.7 million annually. Three variables dominate the factor:
- Benchmark interest rates, which set the lessor’s cost of capital floor;
- Residual value risk, which widens for models facing certification uncertainty;
- Supply-demand scarcity, which is currently acute for both the A321neo and 737 MAX-10 [2].
When the Secured Overnight Financing Rate (SOFR) rises 100 basis points, lessors typically pass through 60 – 80 bps to lessees via escalation clauses, compressing margins for carriers that locked ticket pricing 6 – 9 months forward.
Supply Chain Costs and the Delivery Backlog
OEM production constraints have fundamentally repriced the lease market. Engine availability for the LEAP-1A and GTF fleets remains the binding constraint, with shop-visit turnaround times extending from 60 to 90 – 110 days [3]. This scarcity has two compounding effects:
- New-lease premiums on available aircraft have risen 18 – 22% year over year.
- Sale-and-leaseback (SLB) valuations for mid-life airframes have appreciated, as carriers extend leases rather than face delivery slots in 2031.
For a CFO evaluating an SLB transaction, the effective cost of capital must now include an opportunity-cost premium for forgone fleet modernization – frequently modeled at 150 – 250 bps above the nominal lease rate.
Cost-Benefit: Lease Versus Own
A representative network carrier faces the following annualized economics for a single A321neo:
| Variable | Owned (Debt-Financed) | Operating Lease |
|---|---|---|
| Monthly capital cost | $310,000 | $475,000 |
| Maintenance reserve | Carrier-borne | $45,000 (in rent) |
| Balance-sheet impact | Asset + liability | Off-balance-sheet |
| Residual risk | Carrier | Lessor |
| Fleet flexibility | Low | High |
The lease premium of approximately $1.8 million per aircraft annually purchases optionality: the ability to return airframes at transition, avoid residual-value impairment, and preserve debt capacity for acquisitions. For low-cost carriers targeting 8 – 12% annual fleet growth, this optionality carries an implied ROI exceeding 20% when measured against the cost of constrained expansion [4].
Risk Transmission and Forward Outlook
The central risk in 2026 is rate-factor persistence. Lessors have underwritten current leases assuming SOFR normalizes toward 3.5%; should it remain elevated, re-leasing spreads at transition could add 30 – 50 bps to renewal economics. Conversely, any loosening of engine supply would compress secondary-market premiums rapidly, stranding lessors holding high-basis airframes.
Interest Rate Sensitivity and Asset-Backed Securitization (ABS)
Commercial aircraft leasing operations represent one of the most capital-intensive sectors in global asset finance. Lessors manage vast fleets financed through syndicated loan facilities, private placement bonds, and aircraft Asset-Backed Securitization (ABS) vehicles. Rising benchmark sovereign interest rates exert immediate upward pressure on Lease Rate Factors (LRFs), compelling lessors to structure flexible floating-to-fixed interest rate swaps to insulate operating margins from debt servicing volatility.
Simultaneously, supply chain bottlenecks at major airframe and engine OEMs have constrained global aircraft deliveries, driving robust secondary market valuations for mid-life narrowbody aircraft. Lessors capitalizing on lease extension negotiations achieve attractive cash yields while maintaining disciplined residual value impairment reserves.
Maintenance Reserve Accounting and End-of-Lease Return Conditions
Protecting capital value throughout a multi-year aircraft lease requires rigorous maintenance reserve management. Lessors collect monthly maintenance reserves based on flight hours and cycles to fund major overhaul events, such as engine shop visits and heavy structural C and D checks. Meticulous enforcement of contractual redelivery conditions ensures that returned aircraft meet strict airworthiness directives and technical baselines before transitioning to subsequent airline operators.
Engine Asset Management and Residual Value Insurance Models
In modern aviation economics, aircraft engines account for up to 60 percent of an airframe’s total market value. Commercial lessors manage specialized engine leasing pools to support airline customers during unscheduled engine removals and prolonged OEM supply chain overhaul delays. Financial models must incorporate detailed flight cycle degradation algorithms to project engine shop visit costs accurately and maintain sufficient maintenance reserve balances.
Procuring Residual Value Insurance (RVI) policies provides critical downside balance sheet protection, establishing a guaranteed floor on aircraft asset values at lease termination. This financial insulation allows lessors to secure higher leverage ratios and more competitive borrowing spreads from international banking syndicates, driving enhanced Return on Equity (ROE) across cyclical aerospace market cycles.
Furthermore, structuring pre-negotiated freighter conversion slots for aging passenger narrowbodies provides viable secondary market residual value realization paths as airframes reach their third decade of operational service.
Strategic Executive Summary and Five-Year Implementation Roadmap
To successfully navigate the complex macroeconomic, technological, and regulatory dynamics discussed throughout this analysis, enterprise leaders must deploy a disciplined five-year operational roadmap. Rather than approaching strategic adjustments as isolated technical projects, senior executives and corporate boards must align risk management frameworks, capital budgeting hurdles, and regulatory compliance protocols into a single, cohesive governance architecture.
During the initial phase (Months 1 through 12), the primary objective centers on baseline data integrity, comprehensive asset discovery, and operational risk mapping. Establishing unified telemetry dashboards allows risk committees and department heads to monitor key performance indicators in real time, identifying friction points before they escalate into material financial exposures.
In the intermediate phase (Months 13 through 36), enterprise capital expenditure should focus aggressively on automation, process standardization, and scalable digital infrastructure. Deploying modular technology systems enables cross-functional teams to iterate rapidly while maintaining stringent internal auditability. Contractual vendor negotiations during this window must secure favorable service level agreements, clear indemnification firewalls, and multi-year pricing stability to protect underlying corporate operating margins.
In the final phase (Months 37 through 60), the focus pivots toward institutional optimization, predictive modeling, and sustainable competitive positioning. Organizations that successfully reach this operational maturity level realize significant margin expansion, superior access to low-cost debt and equity capital markets, and sustained brand authority across global commercial ecosystems.
Core Diagnostic Assessment and Key Performance Indicators
Evaluating ongoing operational efficacy requires continuous benchmarking against quantitative industry metrics. Executive scorecards must incorporate both backward-looking financial returns and forward-looking operational resiliency indicators:
- Capital Efficiency Metrics: Tracking Return on Invested Capital (ROIC) and Net Present Value (NPV) benchmarks across all capital deployment initiatives.
- Regulatory Compliance Adherence: Maintaining verifiable third-party assurance audit trails across domestic and international statutory frameworks.
- Operational Friction Reduction: Measuring cycle time acceleration, transactional error reduction rates, and customer lifetime value expansion.
- Balance Sheet Resilience: Establishing dedicated contingency liquidity reserves and stress-tested financial covenants capable of withstanding severe macroeconomic downturns.
By embedding these rigorous performance baselines into executive compensation and board oversight agendas, modern enterprises transform potential industry liabilities into enduring engines of balance-sheet stability and commercial growth.
Aircraft Fleet Financing Economics: Operating Leases vs Finance Leases vs JOLCOs
Commercial airline chief financial officers managing fleet expansion must navigate complex capital financing structures to balance balance-sheet leverage, tax efficiency, and operating flexibility. Under operating lease structures, airlines secure aircraft capacity from global leasing corporations (lessors) for terms typically ranging from six to twelve years, avoiding massive upfront capital outlays while shielding the airline from residual asset depreciation risk at lease expiration. However, operating leases command higher monthly rental payments and impose rigorous maintenance return conditions that can trigger multi-million-dollar restoration penalties if airframes or engines fall below contractual redelivery thresholds.
Finance leases provide an alternative capital structure wherein the airline recognizes the aircraft on its balance sheet alongside an amortizing debt liability, capturing long-term asset equity and depreciation tax shields. For cross-border fleet financing, Japanese Operating Leases with Call Option (JOLCO) structures have emerged as a premier funding vehicle, pairing Japanese equity investors seeking accelerated tax depreciation with commercial bank senior debt. By understanding the intricate mathematical trade-offs between lease rate factors (LRFs), debt service coverage requirements, and residual value guarantees, airline treasuries optimize fleet capital costs across dynamic aviation cycles.
Maintenance Reserve Adjustments and End-of-Lease Restoration Liabilities
A critical operational hazard in commercial aircraft leasing lies in the rigorous calculation and cash management of maintenance reserves (supplemental rent). Commercial lease agreements mandate that airline lessees submit monthly reserve contributions calculated per flight hour and flight cycle to fund future heavy maintenance events, including heavy structural C-checks and D-checks, landing gear overhauls, auxiliary power unit (APU) restorations, and engine performance restoration shop visits.
When an aircraft approaches contractual lease expiry, lessors enforce strict redelivery conditions specifying minimum remaining flight hours and cycles on critical components. If an airline fails to manage engine fleet swap rotations effectively, it may face catastrophic cash redelivery adjustments totaling tens of millions of dollars per wide-body aircraft. Sophisticated airline technical operations teams deploy predictive engine health monitoring and dynamic fleet rotation algorithms that optimize maintenance timing, ensuring aircraft meet redelivery conditions without wasting valuable component green-time.
Strategic Airline Fleet Capacity Optimization Roadmap
Building a resilient airline fleet financing program requires an disciplined multi-stage planning blueprint. In Phase One, airline planning departments execute route-profitability and passenger demand density analyses, matching specific airframe gauge and range capabilities to regional network requirements. In Phase Two, treasury teams structure diversified financing syndicates, balancing operating leases, export credit agency (ECA) guaranteed debt, and asset-backed securitizations (ABS) to avoid refinancing concentration risks.
In Phase Three, technical teams deploy automated fleet maintenance tracking platforms that monitor life-limited part (LLP) consumption and shop visit schedules in real time, synchronizing reserve cash disbursements with actual maintenance milestones. In Phase Four, airline leadership executes strategic fleet roll-over maneuvers, exercising lease return rights or negotiated buyout call options to retire fuel-inefficient airframes in favor of next-generation, low-emission aircraft that compress operating fuel expenditures.
Residual Value Insurance and Asset-Backed Securitization Structures
Aviation finance syndicates managing commercial aircraft lease portfolios frequently utilize specialized Residual Value Insurance (RVI) to optimize debt sizing and capital market securitizations. By transferring aircraft terminal market value risk to investment-grade insurance underwriting syndicates, aircraft lessors can issue asset-backed securities (ABS) with elevated credit ratings and compressed yield spreads. Securing guaranteed residual valuations enables leasing entities to structure attractive lease rate factors for commercial airline lessees while protecting institutional bondholders from unanticipated cyclical downturns in global aircraft secondary market valuations.
Strategic Takeaways and Boardroom Governance Directives for 2026-2030
Executive leadership teams and institutional oversight committees confronting the complexities of Aircraft Leasing Economics in 2026: How Fleet Financing Costs Are Reshaping Airline Margins must transition from passive risk observation to active structural governance. The convergence of strict regulatory compliance mandates, capital allocation hurdles, and rapid macroeconomic shifts demands that organizations establish transparent, data-driven frameworks capable of withstanding external scrutiny. By institutionalizing automated continuous monitoring systems, defining unambiguous delegation of fiduciary authority, and maintaining mathematically defensible audit trails, enterprises successfully eliminate operational vulnerabilities before broader systemic disruptions unfold.
Furthermore, capital budgeting within this specialized operational domain must be disciplined by quantitative hurdle rates and comprehensive total cost of ownership models. Long-term commercial resilience is not achieved through cosmetic compliance exercises; it requires sustained investment in organizational talent, modern technological infrastructure, and independent third-party performance verifications. Forward-looking corporations that embed these empirical principles into daily executive decision-making protect balance-sheet solvency, preserve decisive competitive agility, and secure enduring multi-generational shareholder value across complex global market environments.

