

The Two-Track Carbon Market
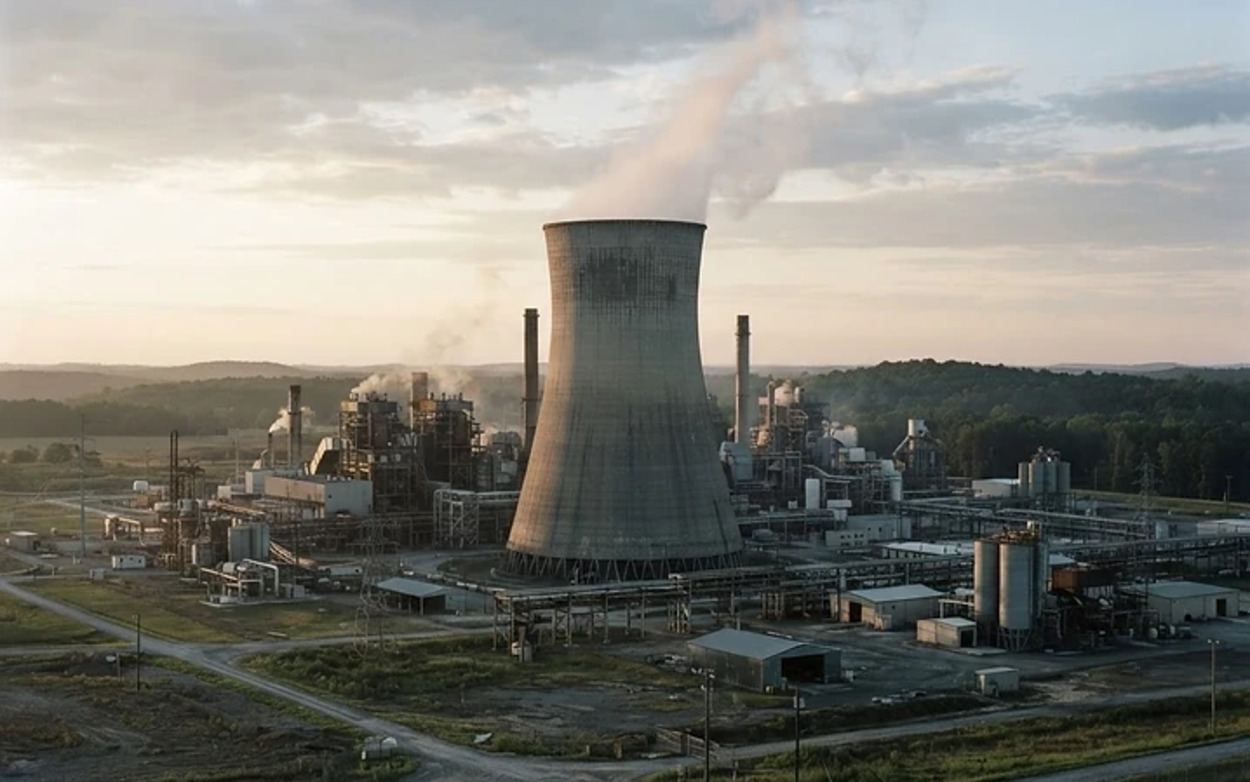
Carbon credit pricing refers to the monetary value assigned to one tonne of CO₂-equivalent abated, traded across two structurally distinct markets. The compliance market — anchored by the EU Emissions Trading System (ETS) and the UK ETS — sets a regulatory price floor through capped allowances. The voluntary carbon market (VCM) prices project-based credits purchased by corporations outside regulatory obligation [1].
The divergence between these tracks has widened sharply. In 2026, EU ETS allowances trade in a €68–€85/tCO₂e band, while high-quality nature-based voluntary credits command $15–$35/tCO₂e, and engineered removals (such as DAC) clear $400–$600/tCO₂e [2].
Compliance Market Drivers
Three forces anchor compliance pricing:
- Cap tightening, with the EU ETS linear reduction factor rising to 4.3% annually from 2024;
- Market Stability Reserve withdrawals, which have removed over 1.5 billion allowances from circulation;
- CBAM phase-in, which extends carbon pricing to imported goods and creates a de facto price floor for embedded emissions[3].
For industrial buyers, the effective carbon cost now equals the allowance price multiplied by verified emissions, plus a shadow price applied to forward capex decisions. Most institutional CFOs apply an internal carbon price of $75–$120/tCO₂e to investment screening.
Voluntary Market: Quality Tiering
The VCM has bifurcated along a quality axis following the 2023 integrity scrutiny. Credits now stratify into three tiers:
| Credit Type | Price Range (USD/tCO₂e) | Vintage Sensitivity | Buyer Profile |
|---|---|---|---|
| Avoided deforestation (REDD+) | $8–$18 | High | Corporate ESG, retail |
| Improved forest management | $15–$35 | Medium | Tech, finance |
| Engineered removal (DAC, BECCS) | $400–$600+ | Low | Institutional, sovereign |
The price spread between the lowest and highest tiers exceeds 75x, reflecting market pricing of permanence, additionality, and measurement uncertainty. Credits failing the Core Carbon Principles now trade at a 60–70% discount to compliant equivalents [4].
Cost-Benefit for Corporate Buyers
A corporation abating 50,000 tCO₂e annually faces a strategic choice. Purchasing Tier-1 REDD+ credits at $12/tCO₂e costs $600,000/year but carries reputational and reversal risk. Investing in internal abatement at a marginal cost of $90/tCO₂e costs $4.5 million/year but is permanent and auditable.
The break-even occurs where the expected cost of reputational damage and future compliance liability exceeds the abatement cost differential. For firms in CBAM-exposed sectors, that break-even has already been crossed — internal abatement now delivers a positive NPV at any discount rate below 12%.
Forward Outlook
The convergence thesis is gaining institutional support. As CBAM and Scope 3 disclosure regimes expand, voluntary credit prices are expected to compress toward compliance benchmarks for equivalent-quality instruments, while low-quality credits face structural devaluation.