

The LCOE Framework
Renewable energy project finance is the structured financing of generation assets — predominantly solar and wind — whose revenue is contracted through power purchase agreements (PPAs) and whose returns are determined by the levelized cost of energy (LCOE) relative to the contracted tariff. LCOE aggregates overnight capex, operating cost, financing cost, and capacity factor into a single $/MWh figure that permits cross-technology comparison [1].
In 2026, unsubsidized LCOE benchmarks stand at:
- Utility-scale solar: $32–$48/MWh;
- Onshore wind: $30–$52/MWh;
- Offshore wind: $72–$110/MWh;
- Battery storage (4-hour): $110–$140/MWh[2].
The Cost of Capital Transition
Because renewable assets have near-zero marginal fuel cost, financing is 70–80% of LCOE. This makes the project’s weighted average cost of capital (WACC) the single most consequential variable. A 100 bps increase in WACC raises solar LCOE by approximately $6/MWh — enough to erode the entire competitive margin over gas peakers in many markets [3].
The financing mix typically comprises:
- 60–70% senior debt at a margin of SOFR + 175–250 bps;
- 20–30% tax equity monetizing transferable credits;
- 10–15% sponsor equity targeting a 6–9% project IRR.
PPA Structuring and Merchant Risk
PPA tenor and price floor determine the project’s bankability. Institutional lenders require a contracted revenue period covering 70% or more of the debt tenor. The shift toward merchant tail exposure — where 20–30% of volume is sold at spot prices after year 10 — has introduced a new risk layer:
| PPA Structure | Contracted Revenue | Merchant Exposure | Debt DSCR | Lender Appetite |
|---|---|---|---|---|
| 15-year fixed PPA | 100% | 0% | 1.35x | High |
| 12-year + merchant tail | 80% | 20% | 1.25x | Moderate |
| 10-year + 5-year collar | 75% | 25% | 1.20x | Selective |
| Full merchant | 0% | 100% | n/a | Equity-only |
The collar structure — a price floor combined with a sold ceiling — has emerged as the dominant mechanism for monetizing merchant exposure while preserving downside protection, typically priced at a 15–25% discount to the fixed-PPA equivalent [4].
Cost-Benefit: Solar Versus Peaker Gas
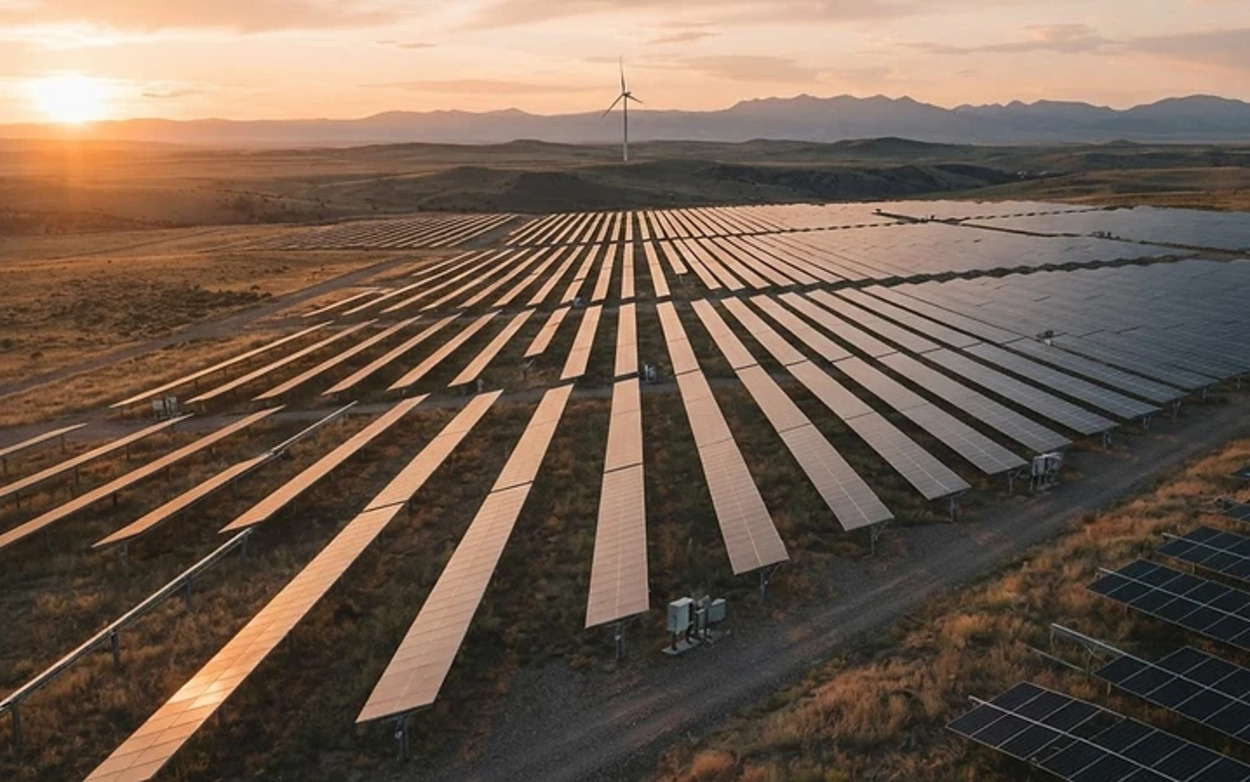
A 200 MW solar project with a 26% capacity factor, $0.85/W capex, and a $45/MWh PPA generates annual revenue of approximately $20.5 million. Against an LCOE of $40/MWh, the project clears a $5/MWh margin, or $2.3 million annually — a 7–8% unlevered IRR. Levered to 70% debt at SOFR + 200 bps, the equity IRR rises to 11–13%, contingent on the capacity factor holding within 1.5 points of underwriting.
The Strategic Verdict
Renewable project finance in 2026 is no longer a technology-cost problem — it is a cost-of-capital and contracting problem. Projects succeed where sponsors secure long-tenor PPAs above $40/MWh, lock WACC below 6.5%, and structure merchant exposure through collars rather than naked tails. For institutional capital, the asset class offers stable, inflation-correlated cash flows, but only when underwritten against realistic capacity factors and disciplined contracting — not against the optimistic yield assumptions that characterized the 2020–2022 build cycle.